Big Tech AI Debt Is Testing Investor Trust
 Vortixel
16 minutes read
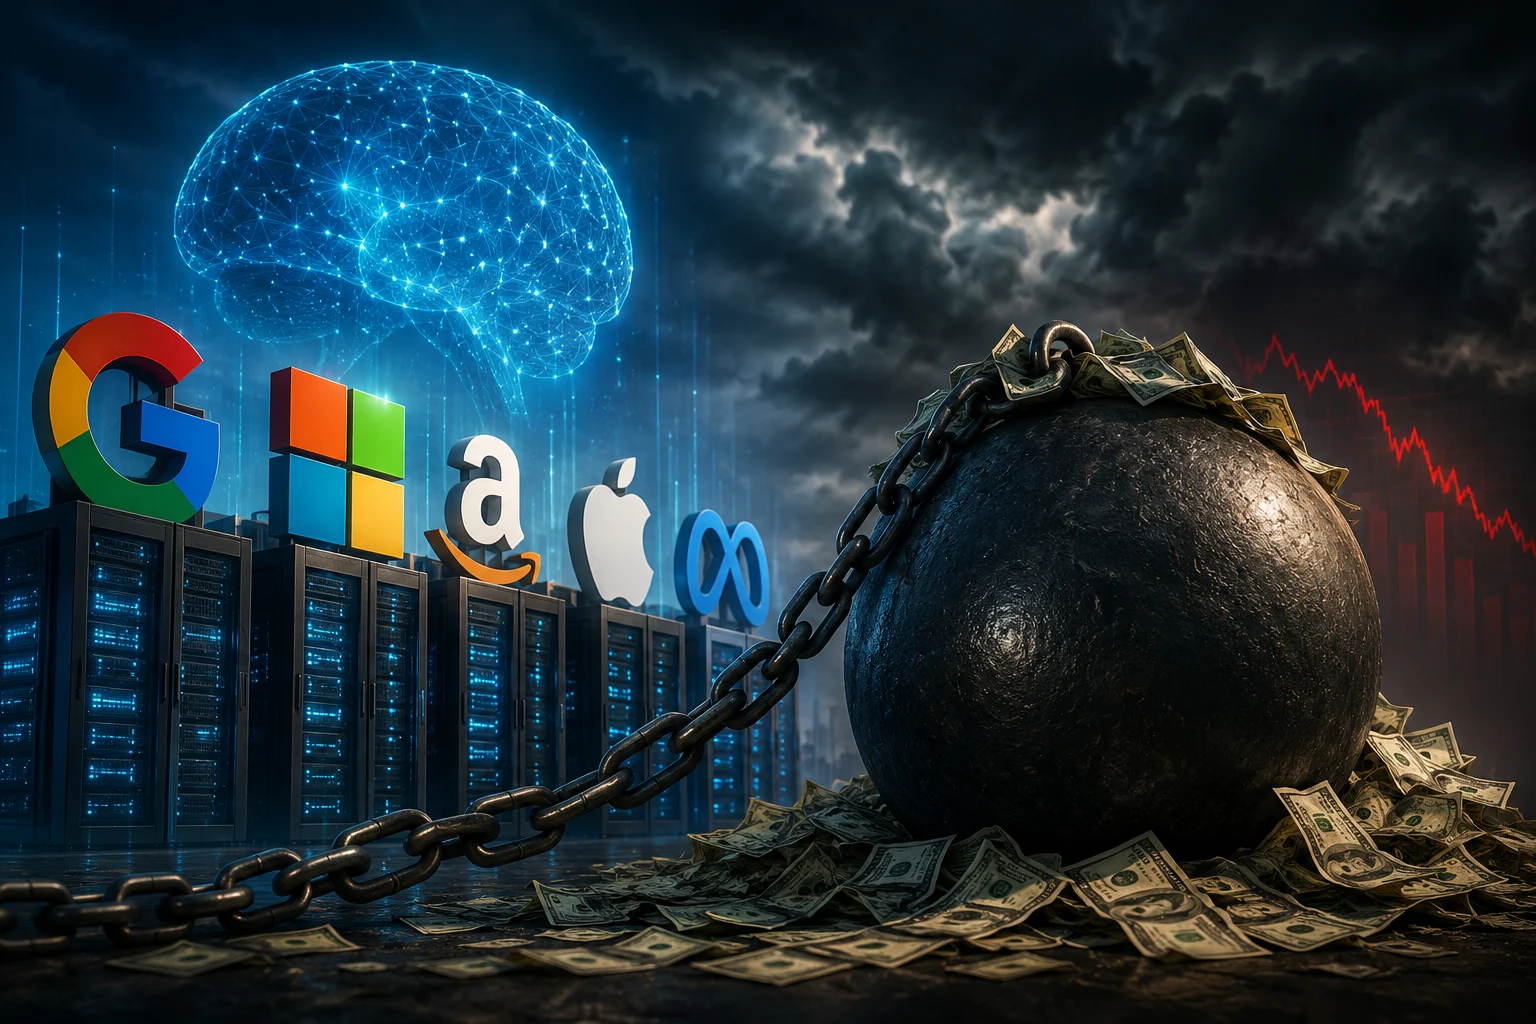
Big Tech AI debt is no longer just a quiet line item sitting inside corporate finance reports. It has become one of the biggest tension points in the modern technology market, where investors are trying to separate real artificial intelligence growth from a spending cycle that could become too heavy to carry. For the past few years, the AI boom has been framed as an inevitable race toward smarter software, faster cloud services, and more powerful automation. Now the conversation is shifting toward something less glamorous but far more important: who is paying for all of this infrastructure, how long the payback period will be, and whether the next wave of revenue can arrive fast enough. That is why the mood around Big Tech AI debt feels different today, because excitement is still alive, but it is sharing the room with caution.
The anxiety is not coming from a belief that AI is useless or that cloud computing is suddenly losing relevance. Investors can see that demand for generative AI tools, enterprise copilots, custom models, chips, data centers, and AI-powered platforms is still growing across the global economy. What worries them is the scale of the financial commitment needed to keep Big Tech ahead of the curve. Building AI at frontier scale requires land, energy contracts, graphics processors, networking hardware, cooling systems, specialized engineering talent, and long-term cloud capacity. When even the strongest technology companies start leaning more heavily on debt markets to fund that buildout, investors naturally begin asking whether the industry is entering a disciplined investment cycle or an expensive arms race.
Why Big Tech AI Debt Is Suddenly a Market Issue
Big Tech AI debt has become a market issue because the AI race is moving from software ambition into physical infrastructure reality. In the early stage of the boom, many investors focused on demos, model releases, chatbot adoption, and productivity promises. Those stories were easy to understand because they looked like classic software growth, where margins can expand quickly once a product scales. But frontier AI does not behave like a lightweight app business, because every major improvement often depends on more compute, more data center capacity, and more energy availability. That turns artificial intelligence from a pure software narrative into a capital-intensive industrial story, and that change affects how investors price risk.
The core concern is simple: AI infrastructure is expensive before it becomes profitable. A company can announce a new model, launch an enterprise AI product, or integrate AI features into a cloud platform, but the infrastructure bill arrives long before customers fully prove how much they are willing to pay. This creates a gap between spending and visible return, and investors dislike uncertainty when the numbers become enormous. In normal times, Big Tech’s strong balance sheets can absorb aggressive investment without causing panic. But when multiple giants raise capital, expand debt, and commit to years of infrastructure spending at the same time, the market begins to wonder whether everyone is chasing the same future too quickly.
There is also a psychological shift happening around AI valuations. During the first wave of generative AI excitement, many investors rewarded companies for showing ambition, speed, and technical confidence. Spending more on AI was seen as a sign that a company understood the future and did not want to fall behind. Now investors are demanding clearer proof that spending will translate into durable cash flow, not just market share defense. That shift matters because the same capital expenditure that once looked bold can start to look risky when revenue growth does not accelerate at the same pace.
The AI Buildout Is Bigger Than Normal Tech Spending
Big Tech has always spent heavily on servers, software development, acquisitions, and global operations. The difference with AI is that the current infrastructure cycle feels larger, faster, and more concentrated than many previous technology waves. Data centers built for AI workloads are not ordinary office expansion projects, because they require extreme power density and advanced cooling systems. The chips inside those facilities are expensive, difficult to secure, and often tied to supply constraints that make timing more complicated. When companies commit to these projects, they are not simply upgrading existing systems; they are building the foundation for a new computing layer that may define the next decade.
This makes the AI race resemble a mix of cloud computing, semiconductor manufacturing, energy development, and real estate investment. A modern AI data center needs reliable electricity, access to fiber networks, specialized hardware, physical security, and regional approvals. It also needs customers who will eventually consume enough AI services to justify the cost of the facility. That is a very different model from launching a social app or a SaaS tool where upfront costs can be relatively small. The more AI becomes embedded in enterprise workflows, the more infrastructure companies need, and the more financial pressure they face to keep building ahead of demand.
The problem is that demand visibility remains uneven. Some enterprise customers are clearly willing to pay for AI tools that reduce support costs, speed up coding, improve analytics, or automate internal operations. Others are still experimenting, running pilot programs, and questioning whether AI features deliver enough measurable return on investment. That creates a mismatch between Big Tech’s infrastructure urgency and the slower adoption rhythm inside many businesses. Investors are not rejecting AI demand, but they are asking whether the current pace of investment assumes a perfect adoption curve that may not arrive on schedule.
Why Debt Makes the AI Race Feel Riskier
Debt changes the tone of the AI conversation because it introduces fixed obligations into a market built on fast-moving assumptions. When a company funds AI investment with existing cash flow, investors may still worry about efficiency, but the risk feels more contained. When debt becomes a bigger part of the strategy, the company must keep servicing that debt regardless of whether AI revenue arrives quickly or slowly. That does not mean borrowing is automatically bad, especially for companies with strong credit profiles and massive cash generation. However, it does mean the market will look more closely at margins, free cash flow, interest costs, and the timeline for AI monetization.
For Big Tech, debt can be rational when rates, demand, and strategic urgency line up. Borrowing can help companies preserve cash, spread infrastructure costs over time, and move quickly while competitors are doing the same. The issue is not debt itself, but the possibility that the industry’s AI spending becomes self-reinforcing. If one giant increases infrastructure investment, another may feel forced to match it, even if the near-term business case is still developing. That creates a competitive cycle where companies are spending not only to grow, but also to avoid looking weak in front of customers, developers, and investors.
This is why investor anxiety is rising even though many Big Tech companies remain financially powerful. The strongest balance sheets in the market can still make poor allocation decisions if the competitive pressure is intense enough. A company may have the ability to borrow cheaply, but that does not guarantee that every AI facility, chip purchase, or model training budget will generate attractive returns. Investors are trained to watch for moments when confidence turns into overbuilding. In the AI market, that fear is especially sharp because the technology is real, but the final business model is still evolving.
The Revenue Question Investors Keep Asking
The biggest question around Big Tech AI debt is not whether AI will create revenue, but whether it will create enough revenue at the right margins. Many AI products are already being bundled into cloud platforms, productivity software, search experiences, developer tools, cybersecurity systems, and enterprise applications. That gives Big Tech many routes to monetize the technology. But AI services can be expensive to run, especially when users expect fast responses, high accuracy, and constant availability. If customers pay only a small premium while compute costs remain high, the margin story becomes less attractive than the headline growth story.
Investors also want to know whether AI revenue is truly incremental or simply defensive. If a cloud provider adds AI features to protect existing customers from switching to a rival platform, that may be strategically necessary, but it is not the same as unlocking a massive new profit pool. If a software company adds AI copilots to justify higher subscription prices, it still needs to prove that customers will renew at those higher prices after the novelty fades. The same logic applies to advertising, search, and consumer platforms. AI can improve products, but improvement alone does not always translate into stronger pricing power.
This is where the market’s patience could be tested. Investors may tolerate heavy AI spending for a while if revenue growth keeps moving in the right direction and executives provide credible guidance. But if AI capital expenditure keeps rising while monetization remains vague, the pressure will build quickly. Analysts will begin comparing infrastructure commitments against actual AI-related revenue, not just overall company performance. That level of scrutiny could force Big Tech leaders to become more transparent about usage, customer adoption, compute costs, and return on invested capital.
Cloud Computing Sits at the Center of the Debt Debate
Cloud computing is the backbone of the AI economy, which is why it sits directly inside the debt debate. The largest cloud platforms are not just selling storage and basic computing anymore; they are becoming AI infrastructure gateways for startups, enterprises, governments, and developers. That makes cloud investment strategically essential, especially as companies build AI agents, automate workflows, and deploy models across global operations. For readers tracking this shift through Cloud Computing, the key point is that AI is making cloud infrastructure more valuable and more expensive at the same time. This dual reality explains why investors can be bullish on demand while still nervous about debt.
The cloud market also creates a winner-takes-more dynamic that encourages aggressive spending. If a cloud provider lacks enough AI capacity, customers may move workloads to a rival with better availability, faster chips, or stronger model partnerships. This means infrastructure delays can become competitive losses, especially for enterprise clients planning multi-year AI strategies. As a result, Big Tech companies may choose to build capacity before demand is fully proven because waiting could be more dangerous than overspending. That logic makes sense strategically, but it does not remove the financial risk from the balance sheet.
There is another layer to the cloud story: startups depend heavily on these platforms. AI startups often need massive compute access before they have predictable revenue, which means they rely on cloud credits, infrastructure deals, partnerships, and sometimes strategic investments from Big Tech itself. This can create an ecosystem where Big Tech funds infrastructure, supports AI startups, and then records cloud growth from companies that are still burning cash. Investors are watching this loop carefully because it can make demand look stronger in the short run than it may be in a more normalized market. If startup funding slows or AI usage becomes more disciplined, cloud growth assumptions could face pressure.
Startups Feel the Ripple Effect Too
The debt anxiety around Big Tech is not only a problem for giant corporations. It also affects startups because the entire AI ecosystem depends on infrastructure pricing, investor confidence, and access to compute. When Big Tech spends aggressively, startups may benefit from better tools, stronger platforms, and more available AI services. But if investors start worrying that the AI boom is overextended, funding conditions can tighten quickly for smaller companies. A startup that once raised money on a bold AI vision may suddenly be asked to prove unit economics, customer retention, and practical efficiency much earlier than expected.
This shift could separate serious AI startups from trend-driven ones. Companies with real workflow value, clear enterprise customers, and strong cost discipline may still attract capital even in a more skeptical market. Startups that rely mostly on vague AI branding, expensive inference, and weak monetization may find the environment much harder. That is not necessarily bad for the ecosystem, because tighter capital can reduce noise and push founders toward better business models. However, it also means the AI startup market may become less forgiving, especially for teams that built products without understanding their compute cost structure.
For founders, the lesson is direct: AI strategy must include financial strategy. It is no longer enough to say a product uses a large language model or automates a business task. Startups need to know how much each user action costs, which model tier is necessary, whether open-source alternatives can reduce expenses, and how pricing scales with usage. They also need to show that their product becomes more valuable over time rather than simply more expensive to operate. In a market worried about debt, efficiency becomes a competitive advantage.
The Bubble Fear Is About Timing, Not Just Hype
Every major technology cycle produces bubble comparisons, and AI is no exception. Some critics argue that the market has priced in years of perfect growth before the business results are fully visible. Others believe the current spending boom is justified because AI will become as foundational as electricity, the internet, or mobile computing. Both views can contain truth at the same time. The real risk may not be that AI fails, but that companies invest too much too early and create financial strain before the market matures enough to absorb the capacity.
This distinction matters because a real technology can still produce an investment bubble. Railways were real, the internet was real, smartphones were real, and cloud computing was real, yet each major cycle included periods of overconfidence, mispricing, and painful resets. AI may follow a similar pattern where long-term impact remains massive while short-term expectations become too stretched. Investors are not simply asking whether artificial intelligence matters. They are asking whether the current price of participation has become so high that even winners could face lower returns than expected.
Timing is especially important because infrastructure assets cannot always be adjusted instantly. A company can slow hiring or reduce marketing spend faster than it can unwind large data center commitments. Once construction begins, contracts are signed, chips are ordered, and energy agreements are arranged, flexibility becomes limited. If demand falls short or pricing weakens, companies may still carry the cost of infrastructure built for a more optimistic scenario. That is why debt-funded AI expansion can make investors nervous even when they believe in the technology’s long-term future.
What Could Calm Investor Anxiety
Investor anxiety around Big Tech AI debt could ease if companies provide clearer evidence of monetization. The market wants to see AI revenue broken down in ways that feel measurable rather than hidden inside broad cloud or software categories. Investors also want stronger explanations of capital spending discipline, including how companies decide where to build, which workloads deserve premium chips, and how they manage utilization rates. If executives can show that AI infrastructure is being used efficiently and tied to profitable demand, debt becomes easier to justify. Transparency will matter because vague optimism is no longer enough for a market watching spending so closely.
Another calming factor would be improving AI efficiency. If models become cheaper to train, cheaper to run, and easier to deploy across specialized use cases, the financial pressure could decline over time. Smaller models, better hardware, smarter routing, and more efficient inference systems could help companies deliver AI features without constantly expanding infrastructure at the same pace. This would make the business model feel more sustainable and reduce fears that every new AI product requires another expensive wave of capital expenditure. In that scenario, Big Tech could keep investing while showing that each dollar of infrastructure creates more output than before.
Stable enterprise adoption would also help. If large companies move from AI pilots into full deployments, revenue visibility improves and infrastructure spending looks less speculative. Enterprise adoption is especially important because businesses tend to sign longer contracts, integrate tools deeply, and generate recurring revenue. Consumer AI products can produce massive usage, but they may be harder to monetize consistently if users resist higher prices. A stronger enterprise AI cycle would give investors more confidence that the debt supporting infrastructure buildout is connected to durable customer demand.
What Could Make the Debt Story Worse
The debt story could worsen if AI spending keeps accelerating while revenue disclosures remain unclear. Investors can accept uncertainty when growth is early, but they become less patient when spending reaches historic levels. If companies continue to raise capital, expand data center commitments, and talk broadly about future demand without showing stronger financial proof, skepticism will increase. The market may also react negatively if AI gross margins disappoint or if companies admit that inference costs are higher than expected. In that environment, even strong quarterly revenue could be overshadowed by concerns about cash flow and long-term returns.
Energy constraints could also make the situation more complicated. AI data centers require enormous power access, and delays in electricity supply can slow projects or increase costs. If companies secure power through expensive agreements, the economics of AI infrastructure may become harder to defend. Environmental scrutiny could add another layer of risk, especially in regions where communities question water usage, grid pressure, and land development. These issues matter because AI infrastructure is not invisible software; it is a physical network with real-world costs and political consequences.
A broader market downturn would create another risk. If interest rates rise, credit spreads widen, or equity valuations fall, the cost of financing AI ambition could increase. Big Tech companies may still access capital better than most firms, but investor tolerance can change quickly when markets become defensive. A weaker macro environment could also slow enterprise technology budgets, delaying AI adoption at exactly the moment infrastructure spending needs stronger revenue support. That combination would make debt-funded expansion look less like strategic confidence and more like financial exposure.
Practical Takeaways for Businesses Watching Big Tech
For businesses, the lesson is not to avoid AI, but to adopt it with discipline. Companies should study Big Tech’s spending cycle as a warning that AI value depends on execution, not hype. Before rolling out AI tools across departments, leaders should define specific use cases, expected savings, revenue impact, data requirements, and security risks. They should also compare the cost of different models, vendors, and deployment options instead of assuming the most advanced tool is always the best fit. In a market where even giants are being questioned over AI spending, smaller businesses cannot afford vague experimentation forever.
SaaS companies should be especially careful with AI margins. Adding AI features can make a product feel modern, but it can also introduce usage-based costs that break traditional subscription economics. If customers use AI heavily while paying a flat price, the vendor may face margin pressure unless pricing is designed carefully. That is why many SaaS teams are moving toward usage limits, premium AI tiers, credits, and enterprise packaging. The smartest companies will treat AI not as a decoration, but as a product layer with its own cost model and value promise.
Cybersecurity teams also need to pay attention because AI infrastructure creates new risk surfaces. More AI tools mean more data movement, more third-party integrations, more automated decisions, and more potential exposure if governance is weak. Companies adopting AI should evaluate vendor security, model access controls, data retention rules, and incident response plans. The financial side of AI debt may dominate investor conversations, but operational risk can become just as important for customers. A sustainable AI strategy must protect both the balance sheet and the data pipeline.
Conclusion: AI Growth Now Has a Balance Sheet
Big Tech AI debt is making investors nervous because the AI boom has entered a more serious phase. The market is no longer satisfied with futuristic demos, broad promises, and endless talk about transformation. Investors want proof that the infrastructure being built today can generate strong, durable, and profitable demand tomorrow. That does not mean the AI story is collapsing, and it does not mean Big Tech has lost its advantage. It means the industry has reached the point where ambition must be matched by financial discipline.
The next chapter of AI will be judged by more than model performance. It will be judged by utilization, pricing power, margins, energy access, customer adoption, and the ability to turn enormous infrastructure spending into reliable cash flow. Big Tech still has the resources, talent, and platform control to lead this transition, but even the strongest companies cannot ignore investor pressure forever. If AI revenue matures quickly, today’s debt may look like smart long-term positioning. If monetization lags, Big Tech AI debt could become the clearest sign that the market’s biggest dream started moving faster than its financial foundation.